
Romina Boccia
The Social Security Administration just announced a 3.6 percent cost-of-living adjustment (COLA) for benefits paid beginning in January 2027. The adjustment reflects the increase in average prices from the third calendar quarter of 2025 to the third quarter of 2026. It will add an estimated $56 billion to Social Security spending in calendar year 2027 compared with leaving benefits unadjusted, according to the Cato Social Security model.
Protecting beneficiaries from inflation is reasonable. But Social Security’s COLA relies on an index with limited population coverage that does not fully account for how consumers respond to changes in relative prices. That means taxpayers are financing benefit increases that exceed those under a more accurate measure of inflation, such as the chained CPI.
Savings from Adopting a More Accurate COLA
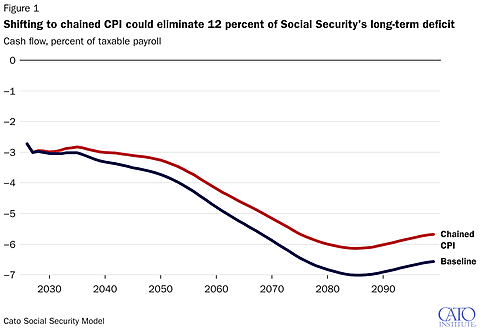
Cato’s modeling estimates that adopting a chained CPI for Social Security COLAs beginning in 2027 would reduce spending by $2 billion in 2027 relative to current law and by $188 billion over 2027–2036. It would close 11.5 percent of the program’s 2032 cash-flow shortfall and 12 percent of its 75-year actuarial shortfall.
The savings accumulate because each annual adjustment affects the benefit base for subsequent years. As such, a small difference in the COLA produces meaningful savings over time. Benefits would generally continue to rise to keep pace with inflation, but more slowly than under the current law.
The Current COLA Relies on an Outdated Inflation Measure
The index Social Security uses to calculate the current COLA, the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI‑W), reflects the spending habits of roughly one-third of Americans. It excludes households with no one in the labor force, including many retirees. It also fails to capture substitution between different categories of goods and services.
Consumers will choose a different basket of goods to adjust to rising prices. For example, when beef becomes more expensive relative to chicken, people might buy more chicken. Economists call this the substitution effect. An inflation measure that misses those adjustments overstates the increase in the cost of maintaining their standard of living.
The Bureau of Labor Statistics addressed this problem nearly 25 years ago. In 2002, it began publishing the Chained Consumer Price Index for All Urban Consumers, or C‑CPI‑U. Unlike the CPI‑W, chained CPI covers 93 percent of the US population and accounts for substitution across spending categories. It generally rises more slowly than CPI‑W and provides a more accurate measure of changes in the cost of living for the average consumer. Social Security also serves disabled workers, survivors, and dependents, making a broader consumer index appropriate for adjusting benefits.
Congress has already embraced this modern index when it meant more tax revenue. The 2017 tax law switched inflation indexing for federal income tax brackets and many other tax provisions to chained CPI. Congress should apply the same measurement principle to Social Security. If chained CPI is appropriate for adjusting taxpayers’ obligations, it should also be used to adjust federal benefits.
Higher Earners Receive the Largest COLA Adjustments in Dollar Terms
Opponents of adopting chained CPI argue that it does not adequately account for the disproportionate health expenses borne by the Social Security population and that it would represent a benefit cut. No broad price index perfectly captures every beneficiary’s expenses. If Congress is concerned that benefits may not keep pace with rising health care expenses, larger COLAs are a poorly targeted way to address the cost of health care.
Because COLAs are proportional to benefits, beneficiaries with higher monthly benefits receive larger dollar increases. According to the Committee for a Responsible Federal Budget (CRFB):
A 3.6% COLA will boost average benefits by about $900 per retiree but would provide an over $2,200 increase for the very richest beneficiaries. The highest-earning couples who retired this year at their normal retirement age will enjoy a $3,600 combined increase — enough to push their combined benefits above $100,000 annually.
If Congress is concerned that a more accurate COLA could cause hardship among vulnerable beneficiaries, it should refocus Social Security’s benefit formula on poverty protection rather than wage replacement instead of using an inaccurate inflation measure to increase benefits across the board.
Adopting Chained CPI is Long Overdue
Adopting chained CPI would not by itself restore Social Security’s solvency. It would, however, reduce excess spending caused by an outdated, limited, and upward-biased inflation formula. With Social Security’s shortfall growing and automatic benefit cuts looming in under six years, every cost reduction matters.
The author thanks Krit Chanwong for providing Cato Social Security model scores. The 2027 no-COLA projection is derived from the 2026 Trustees Report by removing the assumed 2.4 percent inflation adjustment. All other projections are from the Cato Social Security model. We assume that annual inflation, measured by chained CPI, is approximately 0.3 percentage points lower than inflation measured by CPI‑W, and that inflation returns to its assumed long-term trajectory.